
What every real estate investor needs to know before entering this asset class
Mobile home parks have been getting a lot of attention from investors lately, and it is easy to understand why. The returns can be strong, tenant turnover is remarkably low compared to traditional rentals, and on the surface the business model sounds straightforward. Residents own their homes. You collect lot rent. Nobody is calling you to replace a furnace.
But simple-sounding and simple to execute are two different things. That gap is where a lot of investors get caught off guard, and it is usually because they did not fully understand what they were buying before they bought it.
If you have been hearing about this asset class and want to know whether it belongs in your investing strategy, this article will walk you through exactly how it works, what to look for, and what to watch out for.
What You Are Actually Buying
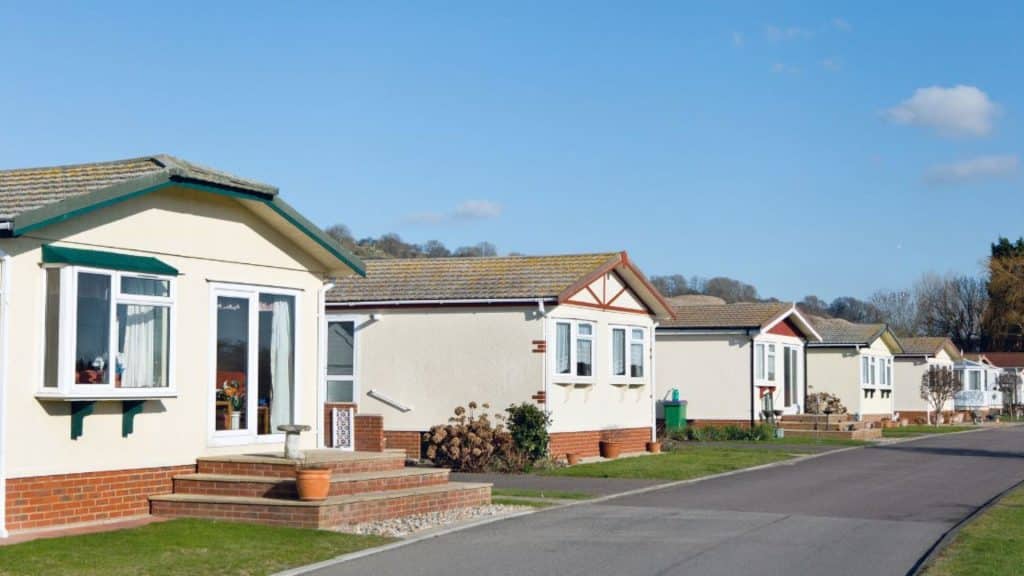
A manufactured housing community, which is the formal name for a mobile home park, is a piece of land divided into individual lots called pads. Residents lease those pads from you and place their own manufactured homes on them. You own the land. They own the home.
That one sentence changes almost everything about how this investment works.
Because the resident owns the home, they are responsible for maintaining it. That removes a significant layer of ongoing cost and effort that comes with traditional rental properties. No appliance repairs, no unit paint jobs, no flooring replacement. Your job is to maintain the land, the roads, and the shared infrastructure.
The other thing this ownership model does is create a resident who really does not want to leave. Moving a manufactured home is expensive, complicated, and in the case of older homes, often not even possible. When someone places their home on a pad and sets up their household, they have made a financial commitment to staying. That stickiness is what makes this asset class behave so differently from apartments or single-family rentals. Annual turnover in a well-run manufactured housing community tends to run well below what you would see in a typical apartment building, and lower turnover means fewer vacant lots, less re-leasing cost, and more predictable monthly income.
How the Income and Valuation Work
If you come from a residential background, the first shift you need to make is in how you think about value.
Residential properties are typically valued on comparable sales. Someone sold a similar house down the street for a certain price, and yours is worth roughly that. Manufactured housing communities do not work that way. Value is driven entirely by income, specifically net operating income, which is the revenue the property generates after operating expenses are subtracted. You take that number and divide it by the capitalization rate appropriate for the market, and that is your value.
This is the commercial real estate model, and if you have not worked with it before, it takes some adjustment. Understanding what your property analysis should actually include is more important in this category than almost any other, because the income statement tells you more about what you own than the physical inspection does.
One mistake worth flagging early: some investors apply the capitalization rate to income from homes the operator owns alongside the lot rent income. Those need to be separated. Manufactured homes are depreciating assets. Applying a real estate cap rate to income from a depreciating asset inflates the value and produces an overpayment that takes years to correct.
The Ownership Structure
Within this asset class, there is an important difference between communities where residents own their homes and communities where the operator owns some or all of them.
In a resident-owned community, your responsibilities are limited to the land and shared infrastructure. This is the model most investors are drawn to, and for good reason. Low turnover, minimal unit-level maintenance, and a resident who has a personal financial stake in keeping the community in good shape.
In a community where you as the operator own the homes, the model changes significantly. Now you are dealing with unit repairs, turnovers, and home upkeep on top of managing the land. Manufactured homes depreciate over time, which means you are holding a depreciating asset on top of an appreciating one. Most experienced operators try to limit the percentage of homes they own, and when the percentage is high on a deal they are evaluating, the price needs to reflect that additional burden.
When you are looking at any specific opportunity, pay close attention to how many homes the operator owns versus how many belong to residents. It is one of the most significant variables in the deal.
What to Check Before You Get Serious About a Deal
Due diligence in manufactured housing has a few specific areas that do not come up in residential investing, and skipping them is expensive. The due diligence process matters more here than in most other asset classes because the surprises tend to be larger.
Start with the utilities. Some communities are connected to municipal water and sewer. Others run on private well and septic systems. If a community runs on private utilities and those systems are aging, a failure becomes your problem to solve, and the cost can be substantial. Before you go deep on any deal, find out what type of utility system is in place and when it was last inspected or replaced.
Rent regulation is the next thing to research. Some jurisdictions have imposed caps on annual lot rent increases. If a deal only makes financial sense because you plan to raise rents significantly over time, and the local regulations will not allow it, the deal does not work. Research the regulatory environment in the specific market before you build any financial model.
Take a hard look at the occupancy numbers too. A seller may tell you the community is mostly full, but vacant lots that have been sitting empty for years are a different story than a recently vacated lot. Filling a vacant lot is not like filling an apartment vacancy. You need to source a home, prepare the pad, pull permits, arrange utility connections, and market to a prospective resident. The timeline can run to months. Underwrite it honestly.
Finally, walk the property. Roads, drainage, and aging utility lines all carry maintenance costs that may not show up in the seller’s historical financials. An inspector with experience in this specific property type is worth the cost.
Understanding The Risks
Every asset class has risks that get underweighted when the opportunity looks attractive. Manufactured housing is no different.
Regulatory risk is probably the biggest one right now. Rent control legislation in various markets has begun to cap lot rent increases. An investor who underwrites a deal on aggressive rent growth assumptions and then encounters a local cap is going to have a problem. This is not hypothetical. It has been happening in a growing number of markets. Do your regulatory research before you commit.
Infrastructure risk runs a close second. Aging utility systems do not announce themselves before they fail. A significant break in a private water main or a failed septic system in a community without adequate capital reserves can produce losses that the operating income cannot absorb. Build your reserves into the financial model from day one.
Operational risk is the one that tends to matter most over time. A manufactured housing community that is not managed with proper systems tends to deteriorate. Resident communication, how promptly maintenance is handled, how consistently collection is enforced, these things determine whether good residents stay long-term. Management quality drives investment quality in this category. The connection between operational discipline and cash flow performance is as direct here as it is in any other asset class.
How Investors Get Started
There are two main ways to invest in manufactured housing communities.
Active ownership means acquiring a community directly and running the operations yourself. This gives you full control over outcomes and the most direct return on your work. It also requires specific knowledge of how these properties are managed, qualified contractors who know this property type, and enough capital to address the issues most communities carry when they change hands. The learning curve is real, and the most reliable way to shorten it is to work alongside experienced operators in this space before going out on your own.
Passive investment through a syndication is the other route. You contribute capital to an acquisition that an experienced operator manages. You receive a share of the income and appreciation without taking on the day-to-day operational responsibility. For investors who want exposure to this asset class while they are still building their understanding of how it works, this is a reasonable place to start. When you evaluate any passive opportunity, focus as much on the operator’s track record as on the specific property they are acquiring.
So, Is This Right for You?
Manufactured housing communities can be a genuinely strong addition to the right investor’s portfolio. The investment characteristics are different from residential real estate, the income tends to be stable, and the supply-demand dynamics in the affordable housing sector are durable. But this is not an asset class you can approach without preparation and expect to do well.
If you have a solid foundation in real estate analysis and you are ready to learn a new set of operational and due diligence skills, this category is worth taking seriously. If you are still building that foundation, add it to your research list and come back to it when the groundwork is in place.


